Introduction & Background
In an era where digital interactions dominate our lives, trust has become one of the most valuable yet fragile commodities. From financial transactions to data sharing, traditional systems rely heavily on intermediaries like banks, governments, and corporations to validate and secure exchanges. However, these centralized structures often introduce inefficiencies, high costs, and vulnerabilities that can be exploited. Enter blockchain technology, a revolutionary innovation that is reshaping the foundations of trust in the digital age. Born from the vision of a decentralized, transparent, and tamper-proof ledger, blockchain is not just a tool but a paradigm shift. It empowers individuals by removing the need for third parties, ensuring that trust is no longer placed in institutions alone but in the immutable nature of cryptographic truth. As industries from finance to healthcare begin to embrace this technology, it is clear that blockchain is more than a buzzword. It is a catalyst for a new era of transparency, security, and autonomy in the digital world.
Concept & Overview
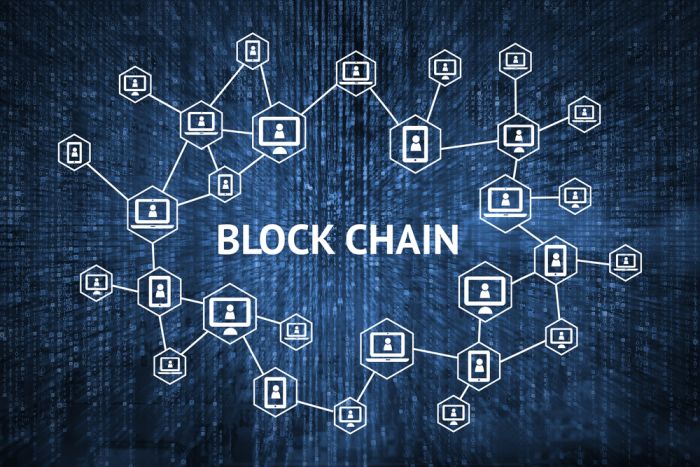
At its core, blockchain is a distributed ledger technology that records transactions across a network of computers in a way that makes them nearly impossible to alter retroactively. Unlike traditional databases managed by a central authority, a blockchain operates on a peer-to-peer network where every participant, or node, holds a copy of the ledger. Each transaction is grouped into a “block” and linked to the previous one through cryptographic hashes, forming a chain of blocks, hence the name blockchain.
This structure ensures that once data is recorded, it cannot be changed without the consensus of the majority of the network. Transactions are verified by nodes through a process known as consensus mechanisms, such as Proof of Work (PoW) or Proof of Stake (PoS). These mechanisms prevent fraud and double-spending, the bane of digital currencies. Additionally, blockchain leverages cryptographic techniques to secure data, ensuring that only authorized parties can access or modify information. By decentralizing control and distributing authority, blockchain fundamentally challenges the traditional models of trust, replacing them with a system where trust is derived from mathematics, code, and collective agreement rather than from fallible human institutions.
Key Features & Highlights
- Decentralization: No single entity controls the blockchain. Instead, the network is maintained by a distributed community of nodes, reducing the risk of centralized failure or manipulation.
- Transparency: All transactions on a public blockchain are visible to participants, ensuring accountability and reducing the potential for fraud. Even in private blockchains, participants can audit the ledger as needed.
- Immutability: Once a transaction is recorded on the blockchain, it is virtually impossible to alter. Cryptographic hashing and consensus mechanisms make tampering detectable and prohibitively expensive.
- Security: Blockchain uses advanced cryptography to protect data. Each block contains a unique hash, and altering a block would require changing every subsequent block in the chain, a feat that is computationally infeasible.
- Smart Contracts: These are self-executing contracts with the terms directly written into code. They automatically enforce agreements when predefined conditions are met, reducing the need for intermediaries and increasing efficiency.
- Consensus Mechanisms: Methods like Proof of Work and Proof of Stake ensure that all participants agree on the validity of transactions without relying on a central authority. This enhances security and fairness in the network.
Frequently Asked Questions / Pros & Cons
What is the main advantage of blockchain over traditional systems?
Blockchain’s primary advantage is its ability to eliminate the need for trusted intermediaries, thereby reducing costs, increasing speed, and enhancing security. Traditional systems often require intermediaries to verify and facilitate transactions, which can introduce delays, fees, and vulnerabilities. Blockchain, by contrast, allows parties to transact directly with each other, with trust being established through cryptographic proof and consensus rather than through a central institution.
How does blockchain ensure security?
Blockchain ensures security through a combination of cryptography and decentralization. Each transaction is encrypted and linked to the previous transaction using a cryptographic hash. This creates a chain of blocks that is extremely difficult to alter. Additionally, the decentralized nature of blockchain means there is no single point of failure. Even if one node is compromised, the network as a whole remains secure because the majority of nodes must agree on any changes.
Is blockchain only used for cryptocurrencies like Bitcoin?
No, while blockchain gained prominence through cryptocurrencies such as Bitcoin, its applications extend far beyond digital money. Blockchain technology is being used in supply chain management, healthcare records, voting systems, intellectual property protection, and even digital identity verification. Its ability to provide a transparent and immutable record makes it suitable for any industry where trust, security, and accountability are critical.
What are the limitations of blockchain?
Despite its many benefits, blockchain has some limitations. One of the most significant challenges is scalability. As more transactions are added to the blockchain, the size of the ledger grows, which can slow down the network and increase storage requirements. Another challenge is energy consumption, particularly with Proof of Work systems like Bitcoin, which require substantial computational power. Additionally, regulatory uncertainty and the lack of standardization across different blockchains can pose obstacles to widespread adoption. Finally, while blockchain enhances security, it is not entirely immune to human error, such as the loss of private keys, which can result in permanent loss of access to digital assets.
Practical Guidance & Solutions
For individuals and businesses looking to leverage blockchain, the first step is understanding which blockchain platform best suits their needs. Public blockchains like Ethereum and Bitcoin are ideal for open, decentralized applications but may lack privacy. Private or permissioned blockchains, on the other hand, offer more control and confidentiality, making them suitable for enterprise use cases.
To get started with blockchain development, learning the basics of smart contracts and consensus mechanisms is essential. Platforms like Ethereum provide tools such as Solidity for writing smart contracts, while frameworks like Hyperledger offer enterprise-grade solutions. Businesses should also consider integrating blockchain with existing systems through APIs or middleware to ensure seamless adoption.
For consumers, using blockchain-based applications requires safeguarding private keys and understanding how to interact with digital wallets. It is important to choose reputable wallet providers and to keep software updated to protect against vulnerabilities. Additionally, exploring decentralized finance (DeFi) platforms can provide insights into how blockchain is transforming financial services, but users should exercise caution and conduct thorough research before participating.
Finally, staying informed about regulatory developments is crucial. Governments worldwide are still grappling with how to regulate blockchain and cryptocurrencies, and compliance with local laws can prevent legal complications. Engaging with blockchain communities, attending conferences, and following industry leaders can provide valuable insights and guidance as the technology continues to evolve.
Conclusion
Blockchain is more than a technological marvel. It represents a fundamental shift in how we establish trust in the digital age. By decentralizing authority, enhancing transparency, and securing data through cryptography, blockchain is redefining the boundaries of what is possible in finance, governance, and beyond. While challenges remain, the potential benefits are too significant to ignore. As adoption grows and innovations like smart contracts and decentralized applications mature, blockchain is poised to become a cornerstone of the digital economy. The decentralized revolution is not coming. It is already here, and it is empowering individuals and businesses to take control of their digital interactions in ways previously unimaginable. The future of trust is not just digital. It is decentralized.